Whether an Insurer Can Drop You for a Chow Chow
One of the most anxiety-inducing aspects of bringing a beautiful, dignified Chow Chow into your life can be the worry about how it will impact your homeowner's insurance. Many responsible owners find themselves in a bind, concerned that their beloved companion might lead to policy cancellation or refusal, simply because of their breed. This guide is here to shed light on how insurance companies view Chow Chows, what your rights are, and how you can proactively protect your home and your furry family member from unexpected insurance challenges.
Understanding Homeowner's Insurance and Dog Breeds
It's a frustrating reality for many dog owners: your choice of canine companion can, in some cases, determine your insurance eligibility or cost. This isn't about your individual dog's temperament or your responsible ownership; it's about statistics and perceived risk from an insurance company's perspective. For a Chow Chow owner, this can feel incredibly unfair, especially when your dog is a well-behaved, loving member of your household.
Insurance providers, at their core, are in the business of assessing and managing risk. When it comes to pets, particularly dogs, the potential for liability claims due to bites or other incidents is a significant factor. Historically, certain breeds have been statistically associated with a higher incidence of severe bite claims, leading to them being labeled as "high-risk" or "dangerous" by some insurers. This blanket approach can be incredibly disheartening, as it fails to account for the unique personality and upbringing of each dog.
The "Dangerous Dog" Breed List Phenomenon
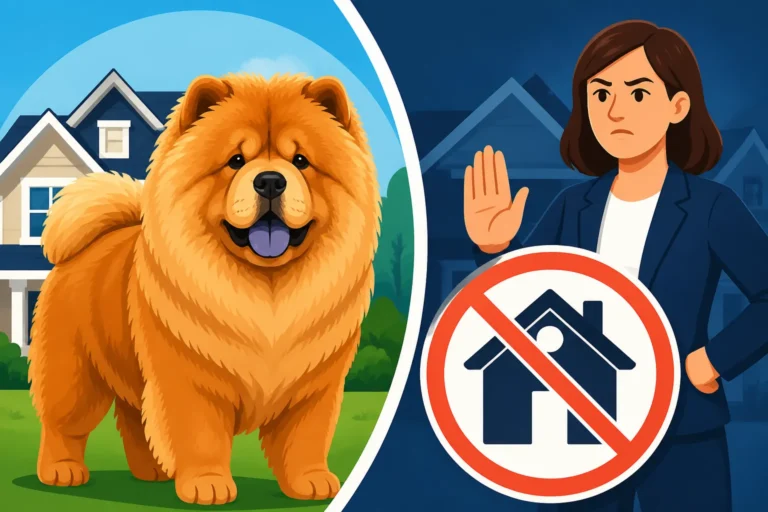
You’ve probably heard whispers or even seen explicit lists from insurance companies or landlords detailing "restricted" dog breeds. Unfortunately, the Chow Chow often finds itself on these lists. This isn't a judgment on your specific Chow Chow, who might be the gentlest soul imaginable, but rather a reflection of broader statistical data that insurers use to calculate their risk exposure. They look at things like jaw strength, size, and historical bite data for the breed as a whole, rather than the individual dog.
It's incredibly frustrating to know that your perfectly behaved companion could be deemed a liability simply because of their genetics. You've poured time, effort, and love into raising a well-adjusted Chow, yet you might face resistance from an insurance provider who only sees a breed name on a list. This generic classification often ignores the nuanced reality that any dog, regardless of breed, can bite if provoked, improperly trained, or neglected. The stigma associated with these lists can make life significantly harder for responsible Chow Chow guardians, forcing them to jump through extra hoops or pay higher premiums.
How Insurers Assess Risk with Dog Ownership
Beyond the dreaded "breed restriction" list, insurers look at several other factors when evaluating the risk associated with dog ownership. They consider the number of dogs in the household, past bite incidents (regardless of breed), whether the dog has a history of aggression, and even if the dog has undergone specific behavioral training. Some policies might inquire about your dog's temperament and whether it has ever been involved in any legal disputes related to biting or aggression.
The challenge for Chow Chow owners is that even if your dog has an impeccable record, the breed itself might still trigger a red flag. This can lead to higher premiums, a demand for special liability riders, or even outright refusal of coverage. It’s a bitter pill to swallow when you know your Chow is a gentle giant, but the insurance company sees only a potential claim. Understanding these criteria helps you anticipate potential issues and prepare yourself for the conversations you might need to have with prospective insurers. It’s also why documentation of your dog’s training and good behavior becomes so important.
Can Your Homeowner's Insurance Drop You for a Chow Chow?
The short answer is: potentially, yes. However, the specifics depend heavily on your existing policy, the laws in your state, and the particular circumstances surrounding your dog. It's not always an automatic denial, but it's a very real possibility that Chow Chow owners need to be prepared for and understand thoroughly. The thought of losing your coverage over your beloved pet is daunting, but knowledge is power here.
Imagine receiving a letter from your insurance company stating they are canceling your policy. For many Chow Chow owners, this isn't just a hypothetical fear; it's a situation they've either faced or constantly worry about. This section will delve into the mechanisms by which an insurer might take such action and what you can do to navigate these choppy waters.
Reviewing Your Policy and State Laws
The first and most crucial step is to meticulously review your current homeowner's insurance policy. Look for clauses related to pet ownership, animal liability, or specific breed restrictions. Many policies will have a "dangerous dog" exclusion or a list of breeds that are either not covered or require additional endorsements. If your Chow Chow is listed, or if the language is vague, it's imperative to contact your insurance provider directly for clarification. Document all communications, including dates, names of representatives, and summaries of conversations.
Beyond your policy, state laws play a significant role. Some states have laws that prevent insurance companies from denying or canceling coverage based solely on a dog's breed. These are incredibly important protections for owners of breeds like the Chow Chow, which often face unfair discrimination. For instance, States That Bar Insurers From Refusing a Chow Chow provides crucial protections, meaning an insurer in these areas cannot simply drop you because you own a Chow Chow without additional cause. Understanding these state-level regulations can empower you when speaking with your insurance agent and help you advocate for your rights.
The Impact of a Bite Incident
While breed restrictions can be a pre-emptive hurdle, a bite incident is almost guaranteed to trigger an insurance review. If your Chow Chow, or any dog, is involved in an incident that results in injury to another person or animal, it can lead to a liability claim against your homeowner's policy. Even a seemingly minor incident can have major repercussions. Insurers will investigate, and if a claim is paid out, it significantly increases your risk profile.
Following a bite incident, your insurer might take several actions: they could non-renew your policy, cancel it outright, or offer renewal only with a significantly higher premium or an explicit dog bite exclusion. This means that any future incidents involving your dog would not be covered. This is why preventative measures like Early Socialization Decides What a Chow Chow Becomes and ongoing training are so vital, not just for your dog's well-being and temperament, but also for protecting your financial security and home insurance.
Proactive Steps to Mitigate Risk
Even with breed-specific concerns, there are many proactive steps you can take to mitigate the perceived risk and present your Chow Chow in the best light possible to your insurer. A well-socialized and trained Chow Chow is less likely to be involved in incidents, which is the ultimate goal. Start socialization early, as a puppy, exposing them to a variety of sights, sounds, people, and other calm, vaccinated dogs in a controlled, positive manner. How Many People a Chow Chow Puppy Should Meet and How Many Car Rides a Chow Chow Puppy Needs are excellent starting points for a young pup.
Consider investing in professional training. Even if your Chow Chow seems to pick things up quickly, structured classes reinforce good habits and give you documented proof of their training. A "Canine Good Citizen" certification, for example, can be a valuable asset. Proper containment, such as a secure fenced yard and always using a leash in public, is also critical. Finally, teach your Chow Chow to be comfortable with a muzzle through positive reinforcement. This isn't about aggression; it's a safety tool for vet visits or emergencies, and proving your dog is comfortable with it shows responsible ownership. Check out Teaching a Chow Chow to Wear a Muzzle for guidance on how to introduce this tool calmly and positively.
Navigating the Insurance Landscape with a Chow Chow
So, you're a proud Chow Chow owner, and you're ready to tackle the insurance challenges head-on. It can feel like a labyrinth, but with the right approach, you can find suitable coverage. The key is to be persistent, transparent, and proactive. Don't assume you'll be rejected; instead, gather your information and approach providers with confidence.
It's true that the process might take a little more effort than for someone with a less "restricted" breed, but it's far from impossible. Many Chow Chow owners successfully maintain robust homeowner's insurance policies. The trick is knowing where to look and what questions to ask, and being prepared for a bit of back and forth.
Finding Dog-Friendly Insurance Providers
Your first line of defense is to actively seek out insurance carriers known for being "dog-friendly" or at least more lenient regarding breed restrictions. Start by talking to independent insurance brokers, as they often work with multiple carriers and can shop around for you. They might have access to specialized policies or lesser-known carriers that don't enforce strict breed bans. Sometimes, smaller, regional insurance companies might have more flexible policies than national giants.
Don't be afraid to be upfront about owning a Chow Chow. Ask directly about their breed policies. Some companies, while not explicitly "dog-friendly," might assess each case individually, especially if you can demonstrate responsible ownership. You can also explore providers like Healthy Paws, which is primarily a pet insurance provider but often understands the broader challenges faced by owners of certain breeds, and they might have resources or recommendations for property insurance. If you struggle to find an insurer willing to cover your Chow, remember that resources like Insuring a Chow Chow When Carriers Say No can guide you through alternative options.
Considering Separate Canine Liability Coverage
If you find that standard homeowner's insurance carriers are unwilling to cover your Chow Chow's liability, or if you simply want an extra layer of protection, considering a separate canine liability policy is a smart move. This type of policy specifically covers damages and legal fees in the event your dog causes injury or property damage to a third party. It acts as a standalone policy, separate from your homeowner's insurance.
This can be a fantastic solution, allowing you to secure homeowner's insurance without worrying about breed restrictions, as the dog-related liability is handled by a different policy. While it's an additional cost, the peace of mind it provides can be invaluable. You can learn more about the costs and benefits by researching What Separate Liability Cover Costs a Chow Chow Owner. It ensures that your beloved Chow Chow is covered, and your home insurance isn't jeopardized.
Documenting Your Chow Chow's Good Behavior and Training
When applying for or renewing insurance, having a portfolio of your Chow Chow's good behavior and training can make a significant difference. Keep meticulous records of all training classes, certifications (like the AKC Canine Good Citizen program), and any special obedience achievements. These documents demonstrate that you are a responsible owner who has invested in your dog's temperament and socialization.
Your veterinarian can also be a valuable resource. Ask your vet for a letter stating your Chow Chow's good health and temperament, noting that there have been no incidents of aggression. Regular vet visits and a clean bill of health reinforce the image of a well-cared-for dog. When it comes to training, even the treats you use matter. High-value rewards from reputable brands like Ollie can make a huge difference in motivation during training sessions, and even proof of consistent training with quality tools from places like Chewy can indirectly show your commitment. These records, combined with consistent positive reinforcement training, can help present a compelling case to insurers that your Chow Chow is a lower risk than their general breed statistics might suggest.
What to Do If Your Policy is Threatened or Canceled
Discovering that your homeowner's insurance policy is being threatened or canceled due to your Chow Chow can be a truly stressful experience. It’s an urgent situation that requires immediate and informed action. Don’t panic, but also don’t delay. Understanding your options and rights is key to navigating this challenge successfully.
Many owners feel singled out or unfairly targeted, and these feelings are completely valid. However, dwelling on the unfairness won't solve the immediate problem. Instead, focus your energy on practical steps to secure new, adequate coverage as quickly as possible.
Understanding Your Rights and Options
If your insurer notifies you of cancellation or non-renewal, they are typically required to provide a reason and sufficient notice. Read this notice carefully. In some cases, there might be an appeal process you can initiate. This is where your detailed records of training, vet visits, and responsible ownership practices become vital. Present your case clearly and calmly, emphasizing your Chow Chow's individual temperament and your commitment to safety.
Should an appeal fail, or if your current insurer is simply unwilling to budge on breed restrictions, your primary option is to seek new coverage. Start immediately, using the strategies outlined previously—contacting independent brokers and researching dog-friendly carriers. Be prepared for potentially higher premiums or the necessity of purchasing separate canine liability coverage. Remember, having a gap in homeowner's insurance can have severe consequences, so act swiftly to secure a new policy before your old one expires. What Insuring a Chow Chow Costs a Month can give you an idea of potential costs, so you are not caught off guard.
Seeking Professional Guidance
Navigating insurance cancellations and finding new policies, especially with a breed on a "restricted" list, can be complex. Don't hesitate to seek professional guidance. An independent insurance broker can be an invaluable ally. They specialize in finding policies for difficult-to-insure situations and have a broader reach into the market than a single-carrier agent. They can often identify smaller, niche insurers or specialized programs that might not be obvious to you.
In rare and particularly challenging cases, especially if you believe you've been unfairly discriminated against or if your state has laws protecting against breed-specific discrimination, consulting with an attorney specializing in insurance law might be necessary. They can help you understand your legal rights and whether you have grounds to challenge an insurer's decision. While most situations don't escalate to this level, knowing it's an option can provide additional peace of mind. Ultimately, the goal is to ensure continuous, comprehensive coverage for your home and family, including your cherished Chow Chow. Responsible Chow Chow owners also need to know that Whether a Chow Chow Suits a First Time Owner or even experienced owners, they will face these unique challenges that other breeds may not encounter.
Disclaimer
This article is for general informational purposes only and does not constitute professional advice. Laws, prices and regulations vary by location and change over time. Consult a qualified professional for guidance on your specific situation.